UK motor 2025: premiums back at 2016 levels, costs down a quarter
Our updated study of 39 UK and Gibraltar motor insurers finds 2025 was another bumper year. In real terms premiums are back where they were in 2016, but implied costs are about 25% lower. Can it last?
Our updated analysis of the UK motor market is now out. It covers the 2025 regulatory disclosures of 39 insurers based in the UK and Gibraltar, around 99% of market gross written premium (excluding Lloyd's and UK branches of non-UK insurers). It updates the preliminary findings we published in May.
Another bumper year
2025 proved to be another bumper year for motor underwriters. Falling rates were accompanied by reduced claim frequencies, and the market confounded forecasters, ourselves included.
- Premium: total gross written premium shrank by 4%, while net earned premium grew by 4%. The spike in rates at the end of 2023 was still feeding through to 2025's results.
- Profitability: disclosed motor combined ratios improved from 89% to 84%. 35 of the 39 firms reported combined ratios below 100%, up from 30 the year before.
- The A-Team: the five largest groups (Aviva, Admiral, Hastings/Advantage, Ageas and Allianz) held their combined share at around 64%, and outperformed the rest of the market by about 7 percentage points.
- Gibraltar: Gibraltar-based firms nudged their share up to 36%.
Not everyone shrank. Hastings added £275 million of premium, the largest absolute increase in the market. Zego more than doubled its premium and Intact grew strongly after acquiring Direct Line Group's broker-intermediated commercial book.
Where did the costs go?
This year we split the results into real-terms changes in premium and in everything else: claims, expenses and reinsurance. Two things stand out. In real terms, average premiums are back where they were in 2016, after the dramatic post-Covid fall. And over the same ten years, implied real-terms costs have fallen by close to 25%.
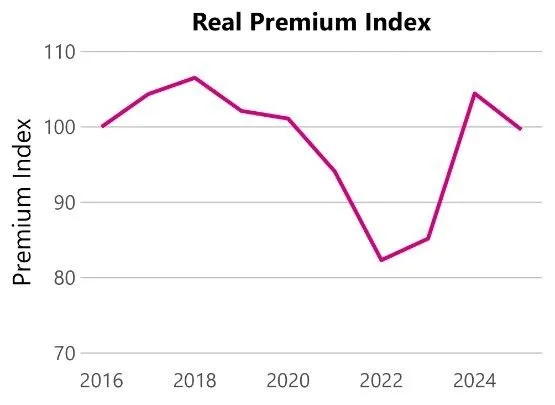
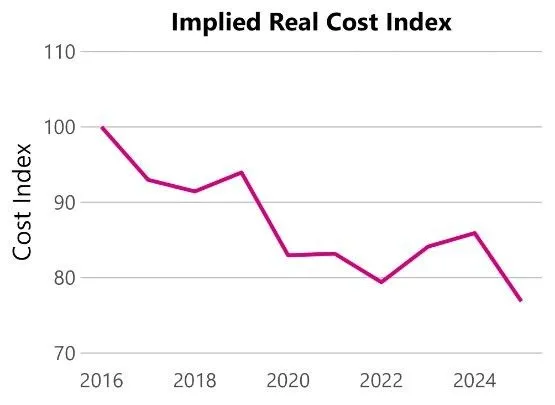
How much of that saving comes from wider societal trends, and how much from the steps insurers have taken, is an open question. Firms cannot take either for granted. Will costs keep being squeezed, or will claimants, helped by AI, find new ways to squeeze unprepared insurers?
Which way for the squeezed middle?
Profits were unevenly shared. The largest firms and the smallest niche insurers both outperformed the 17 mid-sized firms in between, although the A-Team's margin narrowed by around 1.5 points. Will scale and agility keep winning in 2026, or will results flatten as they revert to the mean?
Looking ahead, the picture is complex and some early announcements suggest a deteriorating position. Firms will need to work hard to restore profitability during a time of economic fragility.