Hard Brexit: temporary arrangements by EEA State for the insurance sector
Last edited: 28 March 2019
Hard Brexit remains a possible outcome. What does this mean for UK insurers which write business in the EEA on a passporting basis, and what does this mean for their EEA policyholders?
On 19 February 2019, the EIOPA published a set of recommendations for the insurance sector in light of Hard Brexit, with the “aim to minimise the detriment to policyholders and beneficiaries”. Under these recommendations, EEA competent authorities are advised to:
- facilitate the orderly run-off of businesses which would become unauthorised;
- prevent UK insurers to renew or write new business as long as they are unauthorised.
Each EEA competent authority is given 2 months to respond to these recommendations, either to confirm compliance/ intention to comply, or to explain non-compliance.
To date, not all EEA states have published draft proposals; for those that have, they don’t all adopt the same approach. The table below summarises the proposed temporary arrangements we have located by EEA state. (Note this is a simplified lay reading – please don’t substitute it for legal advice!)
As with all things to do with Brexit, it is constantly evolving – if you know of new developments, do let me know by commenting directly on this Article or email me on feedback@marcuson.co, and I will update the table!
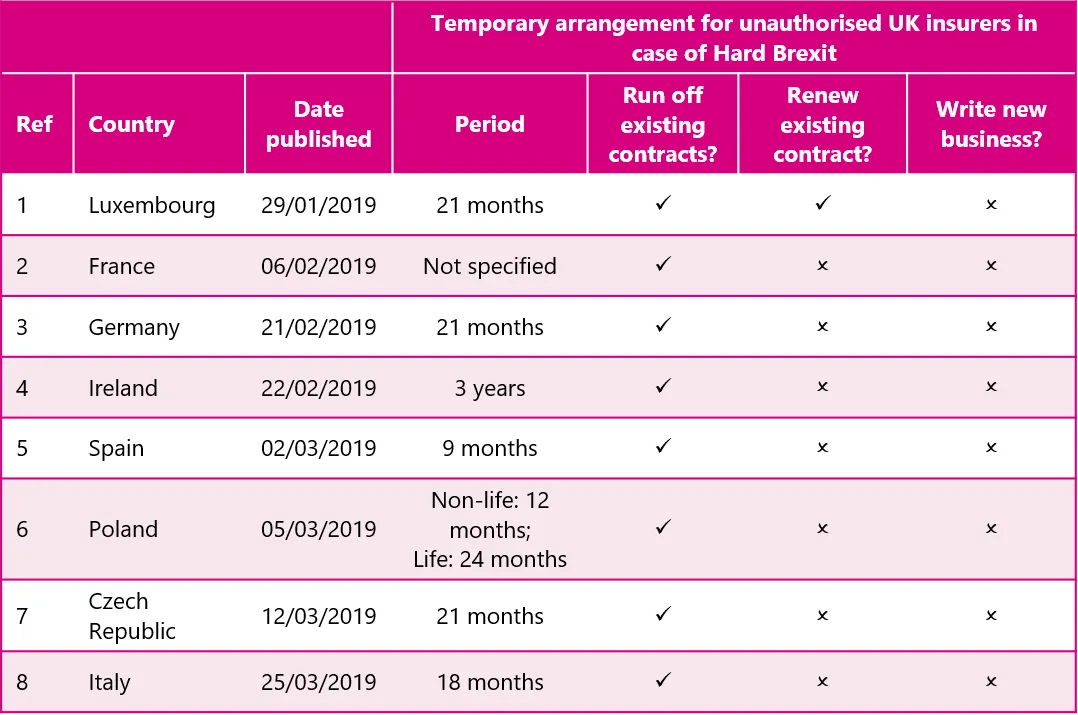
- Luxembourg, Bill n° 7401
- France, Ordinance n°2019-75
- Germany, Brexit-Steuerbegleitgesetz – Brexit-StBG
- Ireland, Part 8, Withdrawal of the United Kingdom from the European Union (Consequential Provisions) Bill 2019
- Spain, Spanish Royal Decree-law 5/2019
- Poland, Art. 6, Draft Law nr 3258
- Czech Republic, § 24, Předpis 74/2019 Sb. (from Clifford Chance's article, increased supervisory extent of Czech National Bank, as if UK insurer were established in Czech Republic)
- Italy, Art. 9, Law Decree No. 22